
Solar Panel Removal & Roof Restoration Financing
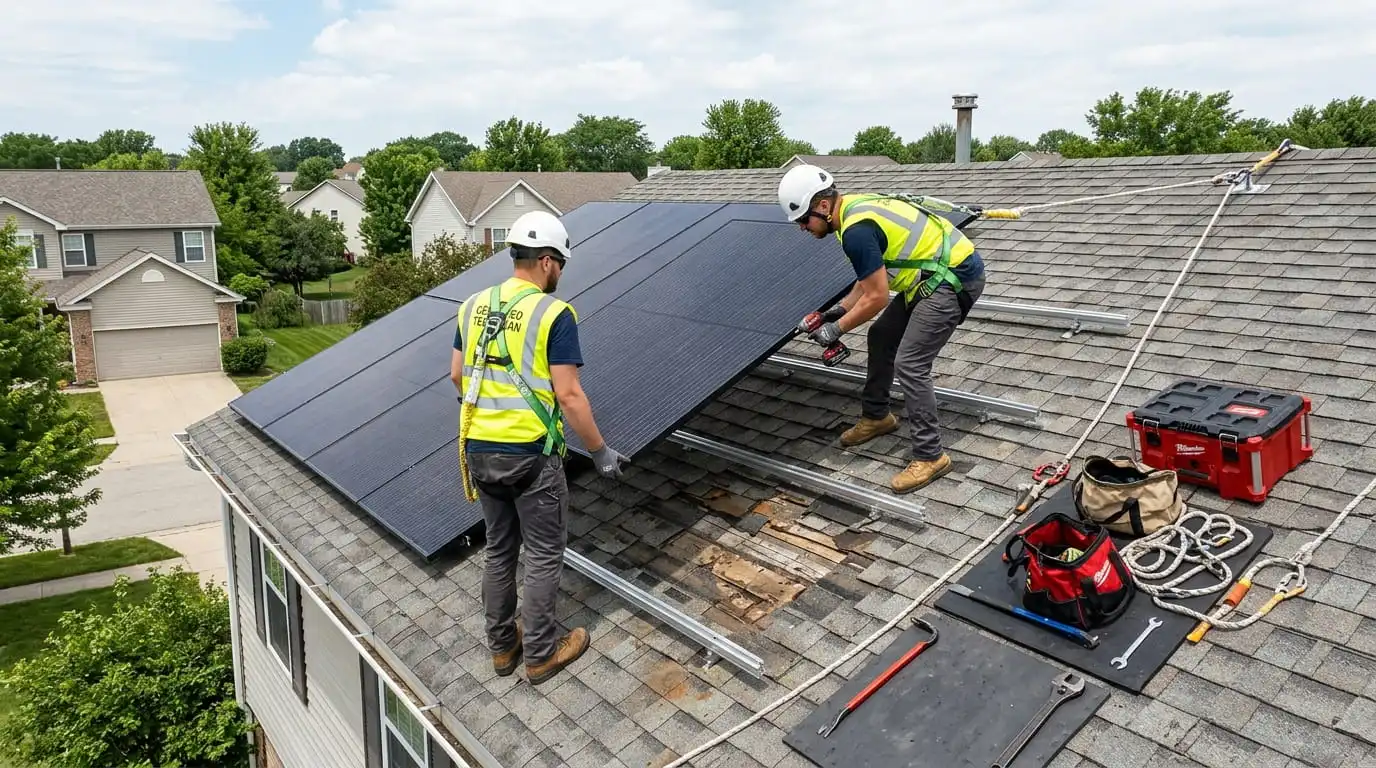
A homeowner is ready to pull down a problematic solar array, but the moment a five-figure teardown and re-roof quote lands on the table, the job stalls. Sticker shock kills momentum, ties up your schedule, and leaves solid revenue sitting on the table.
Solar panel removal and roof restoration financing turns high-ticket quotes into manageable estimated monthly payments through an automated multi-lender platform. Your customer gets the flexible terms they need to say “yes” today, and your business gets paid in full upfront via direct ACH.
Stop waiting on customer milestones or delayed checks. Capital is deposited directly into your business account within 24 to 48 hours of loan completion.
Never lose a client to a single bank’s decline. One quick application cascades across prime, near-prime, and subprime tiers to maximize approval rates.
You are in the contracting business, not collections. Most network programs are non-recourse, once you are funded, you hold zero liability if the homeowner defaults.
Single-lender programs reject too many clients. With our integrated lending engine, every applicant is instantly evaluated across multiple underwriting spectrums. Customers see real, customized options in seconds, allowing you to lock in the job while buying intent is peak.
Solar Exit Financing delivers the complete point-of-sale infrastructure so you can offer client financing with zero balance sheet liability or regulatory headaches. Homeowners can review the fundamentals of installment lending via the CFPB.
| Stage | The Workflow |
|---|---|
Step 1
Instant Soft-Pull Prequalification | The homeowner submits a secure mobile prequalification in under 60 seconds from their phone or your office. There is zero impact on their credit score to explore estimated monthly payment options. |
Step 2
Select the Best Term | Approved borrowers compare competing offers and choose the estimated monthly payment and loan structure that matches their budget. Co-signers and joint applicants are fully supported to strengthen approval terms. |
Step 3
Direct Deposit & Mobilize | Once finalized, project funds are wired via direct ACH into your account within 24 to 48 hours. You order materials and schedule your crew with cash already in hand. |
High-level de-installation, decking repair, and architectural re-roofing involve real overhead, specialized labor, and hard material costs. When clients balk at upfront price tags, too many contractors cut margins or offer risky in-house IOUs that drain cash flow and turn project managers into bill collectors.
Offering point-of-sale financing shifts the conversation from “Can I afford this?” to “Which monthly option fits my cash flow?” You retain 100% of your margins while the lending network assumes all collection and servicing tasks.
Resolving a solar contract dispute or physical removal demands comprehensive capital. Our platform finances the entire scope of work—from panel extraction and major roof restoration to UCC-1 title clearance and provider buyout payouts—bundled into one streamlined application.
Covers complete labor for racking extraction, panel teardown, inverter detachment, electrical capping, and certified transport or disposal.
Funds lag bolt penetration sealing, underlying rotten decking replacements, underlayment repairs, and total structural re-roofing projects.
Enables homeowners retaining their system to finance temporary array removal, roof replacement, and subsequent system reinstallation.
Finances legal filing releases and associated administrative fees to terminate fixture encumbrances that cloud title records.
Finances the full contractual balance required by solar financiers, instantly halting toxic 2.9%–3.5% compounding annual escalators.
Consolidates lease buyout, hardware removal, and complete re-roofing into one easy, predictable monthly payment.
Ranges are illustrative. Final approval, loan caps, interest rates, and loan terms are determined strictly by participating network lenders and borrower qualification.
Complex exits require coordinated payouts. Rather than asking a client to arrange multiple financing plans, a single approved loan covers the entire project invoice. Funds are routed systematically so contractors get mobilized and solar financiers receive payoffs to discharge county liens.
Your client manages a single, fixed installment payment while your firm receives guaranteed funding without administrative drag.
Once the customer selects an offer and final loan documents are signed, your capital is disbursed via direct ACH within 24 to 48 hours. You capture 100% of the contract value upfront, eliminating accounts receivable lag, progress payment disputes, and cash flow crunches.
A $29,000 Full Solar Contract Exit Financing Example Scenario
Here is an operational snapshot of how a full solar exit and roof restoration is funded under a single financing umbrella:
| Project Item | Amount |
|---|---|
| PPA Contract Buyout Settlement | $16,000 |
| UCC-1 Lien Clearance & UCC-3 County Recording | $1,200 |
| System De-Installation & Safe Disposal (Contractor Revenue) | $4,500 |
| Full Roof Restoration & Decking Repair (Contractor Revenue) | $7,300 |
| Total Transaction Financed | $29,000 |
The Outcome: Your client avoids depleting their savings, exchanging an unmanageable lump sum for an estimated monthly payment of roughly $450 to $700 depending on credit profile and term. Your business receives its full contract balance directly via ACH within 24 to 48 hours of loan completion – with zero ongoing collection duties.
Illustrative scenario only. Loan approvals, term lengths, APRs, and monthly payments are determined by participating third-party lenders based on consumer creditworthiness.
Do not treat financing as an emergency measure reserved for price objections. The highest-converting businesses lead with estimated monthly payment options from the very first conversation.
Condition your prospects to expect flexible payment options before price ever becomes a dealbreaker.
Managing in-house payment installments ties up precious working capital, introduces severe default exposure, and consumes endless administrative hours. Point-of-sale financing transfers all operational risk to our lending partners while ensuring your business is paid in full upfront.
| Payment Method | Disbursement Speed | Servicing & Collections | Admin Burden | Ideal Fit |
|---|---|---|---|---|
| Solar Exit Financing | Direct ACH in 24-48 hours | Lender Network | Zero | Full teardowns, re-roofs & buyouts |
| Cash / Check | Immediate upon clearance | None | Minimal | Liquid, high-net-worth clients |
| Credit Cards | 1-3 Business Days | Card Issuers | High Merchant Fees | Minor repair scopes ($500–$2,000) |
| HELOC / Second Mortgage | 30-60 Days (Prolonged Underwriting) | Mortgage Bank | Moderate | Borrowers willing to endure slow closing cycles |
| Internal Payment Plans | Drawn out over months/years | Your Company | Severe Overhead & Risk | High-risk arrangements best avoided |
Offer clients flexible estimated monthly payments while securing your full fee upfront via fast direct ACH funding.
Request a Free Platform DemoHomeowners apply directly via our friction-free digital portal. Applicants submit standard identity, income, and background verification. Specific credit requirements, term durations, APRs, and loan structures are determined directly by lending institutions.
Most financing solutions leverage fixed personal installment loans repaid over predictable monthly intervals. Review consumer installment loan basics via the CFPB.
Initial soft credit prequalification never affects consumer credit scores. Full bureau reporting occurs only if the borrower officially accepts a lending offer. Real-time decisions are delivered within minutes, with merchant funding hitting contractor accounts via direct ACH within 24 to 48 hours of closing.
The financial agreement resides strictly between borrower and lender. With non-recourse financing, homeowner payment delays or defaults have zero bearing on your retained earnings.
If rotten decking or framing failures are uncovered post-removal, simply submit an add-on loan request or secondary financing ticket before launching subsequent phases.
Establish precise terms within your service contract regarding cancellations. Any required loan voiding adheres to verified merchant processing rules prior to job commencement.
Maintain professional, transparent customer representations. Always ensure that technical scopes, roof repair warranties, and solar buyout obligations are documented clearly. Never provide legal, tax, or investment advice without specialized licenses.
Marketing performance or client reviews must reflect truthful representations under federal trade standards. Review regulatory standards via the FTC Endorsement Guides.
If your business loses jobs to sticker shock, deals with delayed payments, or encounters customers who want damaged solar equipment removed but lack immediate capital, this platform is built for you.
Whether you are an independent roofing company, a dedicated solar de-installation contractor, or an exit consultant, offering estimated monthly payments unlocks pipeline bottlenecks, increases average ticket sizes, and protects your margins.
Join our network of elite contractors and solar professionals. Equip your business with a turnkey financing engine that closes deals faster, protects your profits, and delivers upfront ACH funding on every project.
Schedule your walkthrough to see how easy it is to offer point-of-sale financing to your solar exit and restoration clients.
Request a Free DemoImportant: Solar Exit Financing is a financial technology platform, not a lender. All credit approvals, interest rates, term lengths, and loan structures are determined solely by participating third-party lenders. Programs subject to eligibility, credit verification, and merchant partner guidelines. Content is provided for informational B2B purposes only and does not constitute legal, tax, or investment advice.
Help property owners finance early contract terminations and full buyouts while your company secures direct, upfront ACH disbursements upon project approval.
Overcome client budget hesitation on solar dispute retainers and contract audits by offering instant soft-pull financing options with zero impact on credit scores.
Enable homeowners to convert large de-installation and roofing repair quotes into predictable monthly installments, closing jobs faster.
Accelerate UCC-1 fixture payoffs and escrow title clearances so your transactions close on schedule without last-minute financing delays.
Request a platform demo to discover how seamless point-of-sale customer financing helps your business close more cancellation and buyout agreements without managing payment plans.
common questions answered
Yes. You collect the full contract value once the homeowner's loan is completed, deposited by direct ACH and typically within 24 to 48 hours, so your payout lands before you order materials or schedule the crew. There is no receivable to carry and no installments to chase. Coordinate the disbursement and any closing documents with the financing provider so funding clears before you mobilize.
No. You are offering a point-of-sale financing option, not lending money yourself. Solar Exit Financing connects you with licensed third-party lenders who make the credit decisions and hold the loans. Your role is to present the estimated monthly payment as an option, share your financing link, and deliver the work.
Yes. Financing is not limited to full exits. A homeowner keeping their system but needing a new roof can finance the temporary removal, the re-roof, and the reinstallation as one estimated monthly payment. The same applies to panel de-installation, penetration sealing, decking repair, and full roof restoration. You quote the scope, the homeowner finances it, and you are paid upfront on completion of funding.
Handle it as a change order. If the scope grows after approval, the funding amount can be updated before the additional work proceeds, so you are not covering the extra cost out of pocket. Coordinate the revised amount with the lender before you complete the change, and keep your service agreement clear on how change orders and hidden-condition repairs are priced and approved.
Financing covers the full cost of an exit, not just the buyout: lease and PPA buyouts, solar loan payoffs, lien and UCC-1 resolution, panel removal, and roof restoration, all on one plan. Amounts generally range from $1,000 up to $50,000, sized to fit both smaller cancellation costs and larger buyout-plus-removal projects. Final amounts, rates, and terms are set by the lender based on the homeowner's profile.
Financing generally ranges from $1,000 up to $50,000, which covers a single roof restoration or a full buyout-plus-removal bundle. One application is routed across prime, near-prime, and secondary underwriting tiers, so more of your customers receive an offer than with a single bank. Each homeowner prequalifies with a soft credit pull that does not affect their score and sees their exact estimated monthly payment before committing.